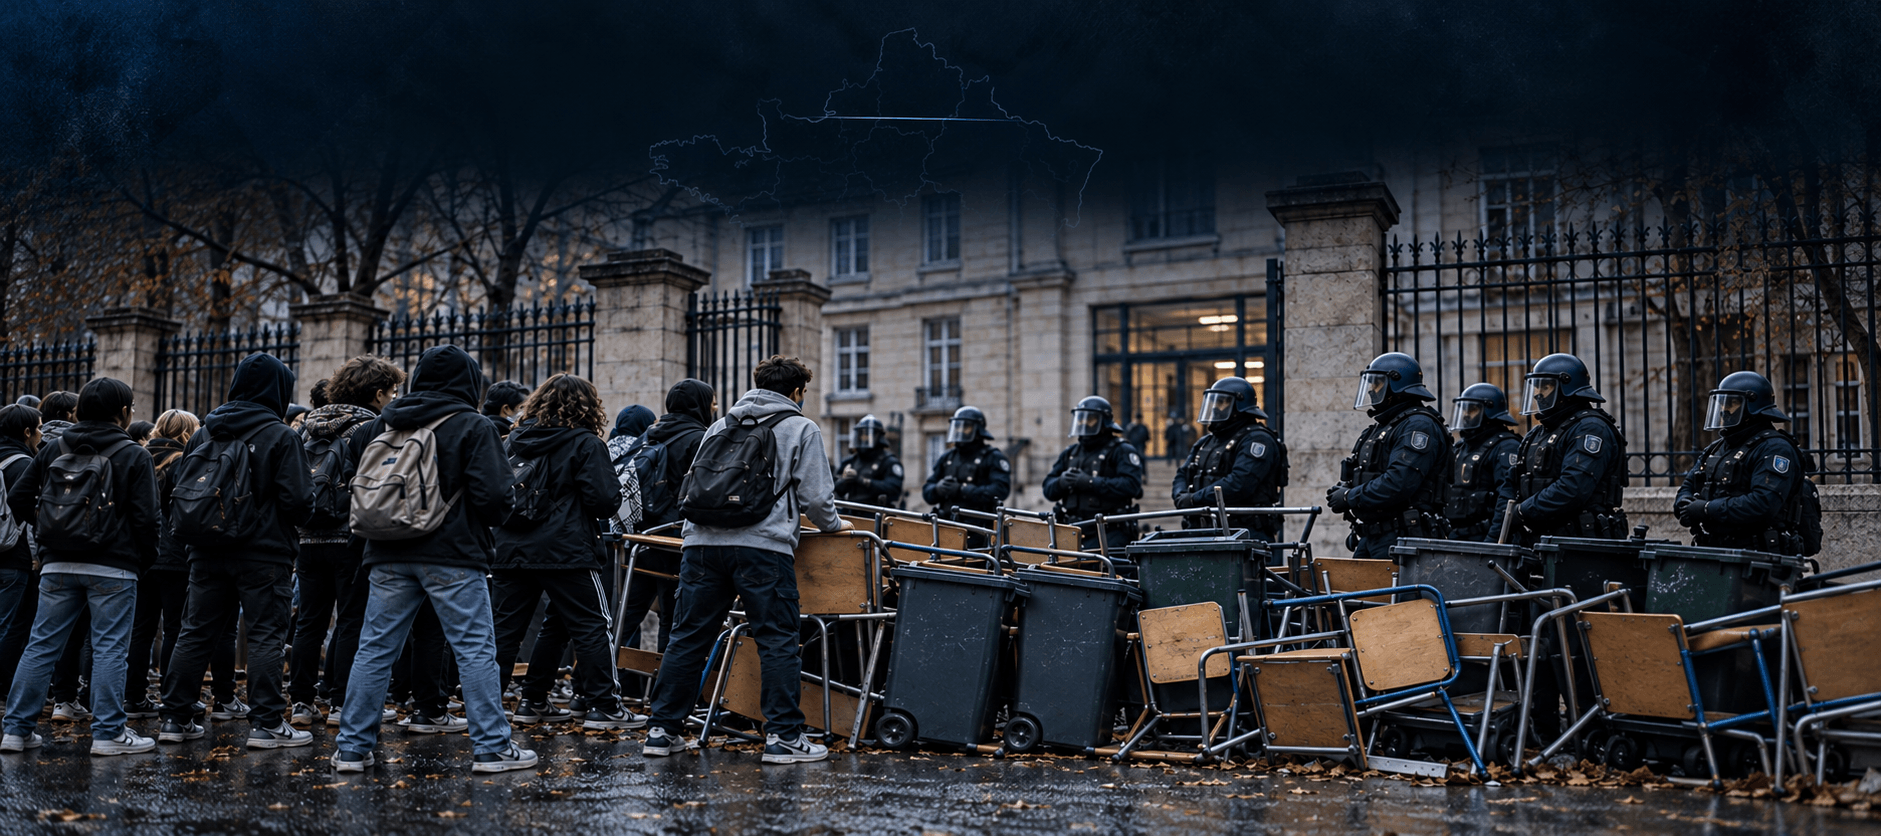
School blockades merged with a public-sector strike against the 2027 draft budget. 440 people were detained and 48 police injured in one day, while Prime Minister Lecornu tries to pass spending cuts with no stable majority.
1. What happened
On Tue 29 Sep, teenagers blockaded about 400 of France’s roughly 3,700 secondary schools over class sizes, teacher shortages and long timetables. Clashes with police followed in several cities, while unions struck against the government’s budget plans.
| Item | Detail |
| Detentions | 440 nationwide, two-thirds placed in police custody, most of them minors (Interior Minister Laurent Nuñez, BFM TV) |
| Police injured | 48; 7 cases of hydrochloric acid thrown at officers |
| Schools affected | About 400 of about 3,700 lycées (education ministry) |
| Hotspots | Paris (Lamartine, Colbert, Hélène Boucher lycées), Seine-Saint-Denis, Lille (bins burned, teargas), Lyon, Villeurbanne, Décines-Charpieu, Bordeaux, Rennes, Nantes, Marseille |
| Student demands | Classes of 32 to 35 pupils, staff shortages, 8am to 6pm timetables (Union Syndicale Lycéenne, president Ryad Rani) |
| Parallel strike | Public-sector unions struck against the budget; about 40% of primary teachers stopped work per unions (FSU, Caroline Chevé); the ministry put strikers at just over 11% of all teachers and staff. CGT leader Sophie Binet gave the government 48 hours to drop the cuts before further action |
| Budget figure | €54 billion of 2027 savings (the Guardian’s “€54m” is a typo; €54bn is confirmed by France 24, Reuters and Bloomberg). Includes a 4th straight freeze on civil-servant base pay (saves €2bn), pension savings and sick-leave changes |
| Political fight | PM Sébastien Lecornu called escalation “irresponsible”; LFI leader Jean-Luc Mélenchon accused the government of a racist crackdown and urged activists to step in |
| Policing | A joint interior and education ministry circular ordered “proportionate use of force” outside schools; the student union called it a scandal |
2. Why it matters
Escalation of an established pattern. It is the second autumn in a row in which a deficit-cutting budget has met strikes and street action. In 2025, the “Bloquons tout” movement of 10 Sep and the union strikes of 18 Sep followed Bayrou’s €44bn plan; Bayrou then lost a confidence vote and was replaced by Lecornu. New this year: minors are the main front line, police violence is now a political issue, and the presidential election is only 7 months away (April 2027).
- The budget is at stake, not just school policy. Lecornu presents the 2027 budget to cabinet on 1 Oct; the bill must reach the National Assembly by 6 Oct. Without the €54bn of savings, the deficit would approach 6.5% of GDP; with them, the target is 5.0% (4.8% excluding defence). Debt is near 120% of GDP, and interest costs rise by about €10bn next year.
- The government has no majority. Socialists call the plan a “bitter austerity potion”. Any concession to students, teachers or unions widens the deficit; any refusal raises the risk of censure. Lecornu could fall the way Bayrou did.
- Unrest is becoming politicised. Mélenchon (LFI) is calling on activists to join the school blockades, and a Seine-Saint-Denis mayor joined one. That extends the protests from schools into the 2027 campaign.
- Growth is weaker than planned. France will grow less than expected in 2026, so each euro of savings is harder to find and each concession costs more.
3. Market impact
The protests themselves do not move markets; the budget they target does. French 10-year debt now yields more than 4.8% and pays a 111bp premium over Germany, double the January level. Unrest that forces concessions or topples Lecornu widens it further.
| Market | Level | Move | Read-through |
| 10-year OAT/Bund spread | 111.2 bp (29 Sep) | +5.8 bp d/d; about 55 bp in Jan 2026 and 86 bp in late Aug | ING sees 100 to 125 bp in coming months; above 120 bp signals a political-fiscal break |
| 10-year OAT yield | 4.83% (30 Sep) | +65 bp m/m; +130 bp y/y; highest since 2008 | France now yields more than Italy’s BTP; each 100 bp adds billions to annual interest over time |
| 30-year OAT yield | 5.44% (30 Sep) | +108 bp y/y | Long-end pressure hits insurers and pension holders of OATs |
| 2027 borrowing | Record €310bn issuance programme (2026) | Debt near 120% of GDP; deficit 5.4% in 2026 | Interest bill up about €10bn in 2027 |
| CAC 40 | About 8,130 (18 Sep); 13-week low 8,141 on 10 Sep | -6.6% over 4 weeks to 10 Sep | Banks and domestic-exposed names most sensitive to OAT spread |
| EUR/USD | 1.128 (1 Oct) | -0.5% d/d on broad dollar strength | France is a euro-area drag, not a euro driver unless the spread passes 150 bp |
| Sovereign ratings | Moody’s Aa3, negative outlook | Fitch reviewed France on 28 Aug | A downgrade during budget turmoil would push the spread past 120 bp |
| Energy, freight, insurance | Not directly affected | n/a | Domestic unrest; ports and refineries not yet in the strike call (see section 7) |
4. Who is affected
French banks and OAT holders carry the market risk; urban retail, transport and anyone running operations near lycées carry the street risk.
| Group | Named players | Effect | Direction |
| French banks | BNP Paribas, Société Générale, Crédit Agricole | Large OAT holdings; share prices track the OAT/Bund spread | Hit |
| Insurers and asset managers | AXA, CNP Assurances, Amundi | Mark-to-market losses on long OATs; 30-year at 5.44% | Hit (but higher yields help new money) |
| Urban retail and hospitality | Carrefour, Casino, Fnac Darty, Accor; city-centre shops in Paris, Lille, Lyon | Footfall drops on protest days; window and property damage risk | Hit on protest days |
| Public transport and outdoor advertising | RATP, SNCF, Keolis, Transdev; JCDecaux (bus shelters vandalised in Lille) | Service cuts on strike days; repair costs | Hit |
| Construction and public contractors | Vinci, Eiffage, Bouygues | Public capex cuts in a €54bn savings budget | Negative |
| Education and public sector | 12 million pupils, about 850,000 teachers; FSU, CGT, SNES, USL | Pay freeze (4th year), staff shortages, class sizes of 32 to 35 | Hit |
| Euro-area peers | Italy BTP, Belgium OLO | Contagion if the OAT spread jumps; Italy already trades tighter than France | Mild negative |
| Defence | Thales, Dassault Aviation, Safran | Defence is ring-fenced (deficit target 4.8% excluding defence) | Protected |
Geographies: Paris and Seine-Saint-Denis; Lille (worst violence); Lyon and its suburbs (Villeurbanne, Décines-Charpieu); Bordeaux, Rennes, Nantes, Marseille.
Supply chains at risk: none yet. Risk rises if the CGT widens action to refineries (TotalEnergies), ports (Le Havre, Marseille-Fos) or rail freight, as in past budget and pension fights.
5. Scenarios (next 2 to 8 weeks, to late Nov 2026)
The trigger window is the budget’s first reading: cabinet on 1 Oct, filing by 6 Oct, Assembly debate through October and November. The October half-term (about 17 Oct to 2 Nov) naturally pauses school blockades. Probabilities are our estimates.
| Scenario | Trigger | Probability | OAT/Bund spread | Impact |
| De-escalation | Government offers targeted education measures (smaller classes in priority zones, staffing hires); policing eases; half-term cools blockades; PS abstains rather than censures | 25% | Back to 90 to 100 bp | Budget passes first reading with tweaks; protests fade to one-day union actions |
| Base case | Rolling union strike days after CGT’s 48-hour ultimatum; sporadic lycée blockades before and after half-term; budget debated amid partial concessions that trim savings to about €45bn to €50bn | 50% | 105 to 125 bp | Deficit target slips toward 5.2% to 5.4%; ratings pressure; city-centre disruption 1 to 2 days a week |
| Escalation | A serious injury or death of a minor in a police clash; LFI-led mobilisation; PS joins a censure motion; Lecornu falls or the budget is pushed into a stop-gap “special law” | 25% | Above 125 bp, possible test of 150 bp | Repeat of Bayrou’s fall in 2025; budget delayed into 2027; refinery or port strikes; rating downgrade risk |
6. Actions to consider
Plan for a weekly strike-day rhythm in French cities through November, and hedge for the OAT/Bund spread passing 125 bp if the budget or the government breaks.
Finance and treasury
- Stress-test French exposures at a 150 bp OAT/Bund spread and a one-notch rating downgrade; cap new long-dated OAT buying until the first reading passes.
- Lock euro funding for French entities now; French bank credit spreads widen with the OAT spread.
- If you sell to the French state or municipalities, model 5% to 10% lower 2027 public contract volumes and slower payment.
Operations and people
- Track union strike calendars (CGT, FSU, SNES) and the student union USL; set a work-from-home trigger for staff in Paris, Lille and Lyon on announced days.
- Avoid scheduling deliveries, events or store activations near lycées in Paris (north and east), Seine-Saint-Denis, Lille, Lyon and Villeurbanne on school-blockade mornings.
- Review property insurance and security for street-level sites (shopfronts, advertising panels, bus shelters) in hotspot cities.
Logistics and supply chain
- Add 3 to 5 days of buffer for France-routed freight in case strikes widen to SNCF freight, Le Havre or Marseille-Fos.
- Pre-book alternative routing via Antwerp, Rotterdam or Barcelona for time-critical cargo.
Legal
- Check whether strikes and civil unrest count as force majeure in French supply and service contracts; send notices early if delays occur.
- For multinationals with French workforces, prepare for unions to reopen pay talks if the civil-service pay freeze passes.
7. What to watch next
The decisive signal is the Socialist Party: if it signals it will back a censure motion, Lecornu’s government and the €54bn plan are in real danger.
| Indicator | Who / when | Current reading | Trigger and inference |
| Budget unveiling | Cabinet, 1 Oct; filing deadline 6 Oct | €54bn savings; deficit target 5.0% | Any added education money signals concession; a bigger savings figure signals confrontation |
| CGT ultimatum | Sophie Binet; 48 hours from 29 Sep | Expired around 1 Oct | Inter-union call for a national strike day = base case confirmed; renewable strikes = escalation |
| School blockades | USL, interior ministry tallies; daily | About 400 of 3,700 lycées hit; 440 detained on 29 Sep | Over 500 schools or a serious injury = escalation; under 100 = fading |
| Policing and politics | Interior Minister Nuñez, LFI, Défenseur des droits | Circular on “proportionate force”; Mélenchon accusing racism | An IGPN probe or viral video of abuse would widen protests |
| Socialist Party stance | PS group in National Assembly; October | Called the plan “bitter austerity potion” | Threat to back censure = high risk to Lecornu |
| OAT/Bund spread | Daily | 111 bp | Above 125 bp = markets pricing a government fall |
| Rating actions | Moody’s, S&P, Fitch | Moody’s Aa3 negative | Any downgrade during the debate accelerates the spread move |
| Sector strikes beyond schools | SNCF, RATP, refineries, ports | Public-sector and firefighters only so far | Refinery or port strike calls = supply-chain risk |
| Opinion polls | Ifop, Elabe; weekly | Government and Macron deeply unpopular | Majority public support for students raises pressure to concede |
8. Bottom line
France saw 440 detentions and protests at about 400 of its 3,700 lycées in one day, merging with strikes against a €54bn austerity budget. With the OAT/Bund spread at 111 bp and no majority, a government fall would push it past 125 bp.